
Autopilot - Investment App
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Autopilot - Investment App - Screenshots
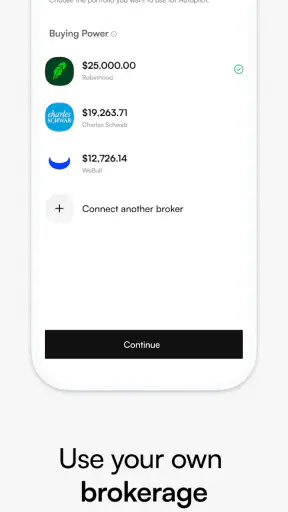
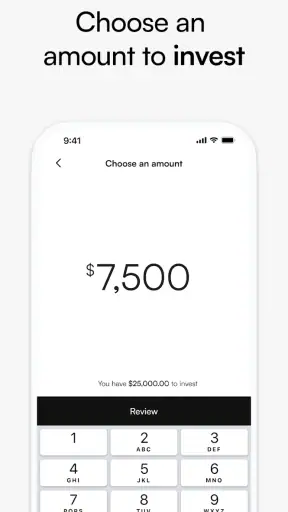
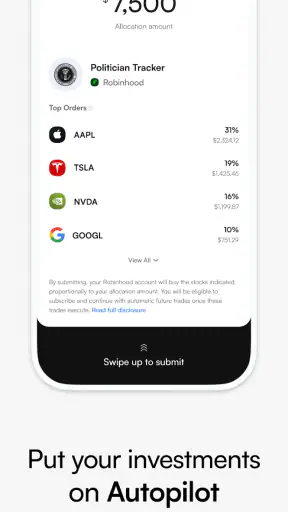
Pros
- Automates recurring investments
- helping maintain a consistent investing routine.
- Simple portfolio overview makes it easy to monitor holdings and contributions.
- Supports goal-based planning for users saving toward specific financial targets.
- Useful educational content can help beginners understand basic investing concepts.
- Mobile access lets you review account activity and investment progress anywhere.
Cons
- Investment options may be limited compared with full-service brokerage platforms.
- Automation does not eliminate market risk or guarantee positive returns.
- Some features or account types may require paid plans or additional fees.
- Portfolio customization may be insufficient for experienced investors.
- Identity verification and account setup can take time before investing begins.
Autopilot - Investment App - Description
- App Name
- Autopilot - Investment App
- Package Name
- finance.iris.autopilot
- Developer
- Autopilot Holdings Corporation
- Category
- Finance
- Last Updated
- Nov 15, 2023
- Version
- 1.19.25
I approached Autopilot as a finance app for people who want investing to feel less intimidating, but I also judged it by a stricter standard: how comfortable would I be handing it a place in my financial routine? Its promise is appealing because many people want to start investing without spending every evening comparing companies, charts, and market commentary. At the same time, an investing app deserves more careful scrutiny than an ordinary utility. Convenience is useful only when the user still understands what is happening and can make deliberate choices.
Developed by Autopilot Holdings Corporation, the app is free to download and is rated for Everyone. It has attracted over a million installs, with a 4.7 average from around seven thousand ratings. Those figures suggest that the product has found a sizeable audience, although popularity alone is not proof that it suits every investor. I found its strongest appeal in the way it presents investing as a guided activity rather than an endless research project. Its weakest point is the same thing: a simplified experience can make decisions feel easier than they really are.
What the experience feels like when trust matters
The first thing I noticed is that Autopilot is not best understood as a replacement for a full brokerage workstation. It is aimed more at the person who wants a clearer route into investing, or at an existing investor who prefers a more focused way to follow a chosen approach. That distinction matters. If you enjoy studying earnings reports, comparing order types, or building detailed screens, a traditional brokerage may give you more control. If you tend to postpone investing because the choices feel overwhelming, a guided app can remove an important barrier.
I would not treat the app’s modern presentation as a substitute for learning basic investing principles. Before connecting any financial account or committing money, I would want to understand what the selected strategy is trying to do, how much control I retain, and what actions may happen after setup. The right mindset is to use Autopilot as a tool for carrying out an informed plan, not as an authority that can decide whether an investment is suitable for me.
The developer’s identity is visible as Autopilot Holdings Corporation, and the app’s current version is 1.19.25. That version detail is useful when discussing support or troubleshooting because an older installation can behave differently from the current release. The minimum operating-system requirement is version 10, so I would check compatibility before planning to use it on an older phone. On a supported device, the free entry point makes it easy to inspect the experience before deciding whether it belongs in a real financial workflow.
Starting without rushing into a deposit
My practical advice is to separate exploration from commitment. Install the app, read each screen carefully, and notice which choices are optional, which are required, and which lead directly toward an account connection or investment action. This simple pause is especially important with finance products because a polished onboarding flow can encourage people to tap through faster than they would read a brokerage agreement on a desktop.
I would also prepare a short personal checklist before using it: my goal, my time horizon, the amount I can genuinely leave invested, and the level of loss I could tolerate without abandoning the plan. That checklist gives the app a role in my process without allowing the app to define my process. It also makes it easier to spot when a suggested approach does not match my circumstances.
Controls I would inspect before trusting the workflow
Trust in an investment product is built through visible controls, not just friendly language. I would look for clear ways to review connected accounts, change or stop an investing instruction, inspect pending actions, and confirm where money is going before anything is finalized. I would also want important actions to require an unmistakable confirmation rather than being hidden behind a casual swipe or a vague button.
These checks are not merely technical preferences. They determine whether I remain the decision-maker. An app can make investing convenient while still giving me enough information to pause, correct an error, or change direction. If a screen presents a strategy without making its consequences easy to understand, I would slow down and seek clarification rather than assuming the default is appropriate.
Account control is equally important after setup. I would expect to be able to review my profile, manage linked financial relationships, and understand how to stop using the service. A good routine is to revisit those settings periodically instead of treating onboarding as a one-time event. This is particularly useful after changing banks, replacing a phone, or deciding that a particular investing approach no longer fits.
One non-obvious trade-off is that a streamlined interface may reduce the number of decisions I need to make while also reducing the number of details I see at first glance. That is helpful when I am distracted or inexperienced, but it can be limiting if I want to investigate every assumption. I would therefore use the app’s simplicity for execution, while doing more detailed research elsewhere when the decision involves a large amount of money or a major change in my plan.
Data-sensitive moments deserve extra attention
Finance apps naturally bring sensitive moments into the foreground. The most important ones are account creation, identity-related steps, financial-account connections, notifications, and any action involving transfers or investments. At each point, I would read the wording instead of assuming that a request is routine. I would also check whether the app explains why a permission or piece of information is needed and whether there is a less invasive way to continue.
I am deliberately cautious about permissions because a finance app should not receive broad access simply because I want its core service. On my phone, I would review the operating system’s permission panel after setup and again after an update. If a permission seems unrelated to the task I am performing, I would leave it disabled until I understand its purpose. This is a practical habit, not an accusation: visible permission choices let me keep the app’s access aligned with how I actually use it.
Notifications also deserve a thoughtful setup. Investment alerts can be useful when they confirm an action or draw attention to something requiring review, but constant market-related prompts can encourage reactive behavior. I would keep only the notifications that help me verify activity or meet a genuine responsibility. Turning off unnecessary alerts can make the app less intrusive and reduce the temptation to make emotional decisions based on every movement.
Another useful habit is to avoid doing sensitive account work on a public network or while multitasking. I would verify the app name and developer before entering credentials, keep the phone’s operating system current, and use a strong device lock. These steps are not special features of Autopilot; they are part of using any financial service responsibly. The app can provide a convenient interface, but it cannot replace careful device and account hygiene.
Keeping control over an everyday investing routine
A realistic use case would be someone who receives income, pays regular expenses, and wants to invest consistently without checking markets during every lunch break. I could see that person using Autopilot to follow a previously considered plan, then reviewing activity at a fixed time each week or month. The value would come from reducing friction and creating a repeatable habit, not from trying to predict what the market will do tomorrow.
In that scenario, I would keep a separate record of the intended contribution, the chosen approach, and the reason for using it. After the first activity, I would compare that record with what actually happened in the app. This catches misunderstandings early, especially if the user expected a manual decision but the workflow handled more of the process automatically. It also prevents the app from becoming a black box in my personal finances.
For a beginner, I would start with an amount that would not disrupt rent, bills, emergency savings, or near-term plans. The app’s free price removes one obvious barrier to trying it, but free access does not remove investment risk. I would never interpret a smooth setup process as evidence that an investment is safe, guaranteed, or suitable for a short deadline. Money needed soon belongs in a different planning conversation.
For an experienced investor, the use case is narrower but still possible. Autopilot may be attractive when I want a simpler interface for a defined strategy and do not need the full collection of tools found in a conventional brokerage. However, I would skip it if I need advanced order handling, extensive tax documents, detailed research, or highly granular portfolio construction. In those situations, a more established all-purpose investment platform is likely to be the better fit.
Where it compares well, and where alternatives win
Compared with managing investments through a bank, Autopilot can feel more focused and less buried inside a broader collection of financial services. Compared with a traditional brokerage, its appeal is the reduction of clutter and decision fatigue. Compared with a passive savings product, it belongs to a different category altogether: investing involves uncertainty, while saving for a near-term goal calls for stability and access to cash.
The comparison is not simply about which interface looks better. A traditional brokerage usually makes more information and controls available, which is valuable for users who want to make every decision themselves. A focused app can be easier to approach, but that convenience may come with fewer visible details or fewer ways to customize the process. I would choose based on the job I need done rather than assuming the simpler product is automatically superior.
Autopilot is also not the right answer for someone who wants personal financial advice tailored to debt, insurance, taxes, retirement income, and family obligations. An investing interface can help with an investment task, but it does not replace a complete financial plan. If my situation were complicated, I would use the app only as one component of a broader process and consider speaking with a qualified professional.
Three habits that make the app safer to use
- Use a review-before-action rule: before confirming anything, I would check the destination, amount, timing, and strategy shown on the final screen. A few seconds of verification is worthwhile when an action affects real money.
- Separate automation from supervision: I would set a calendar reminder to inspect activity and account connections rather than assuming that an automated workflow can be ignored indefinitely. Automation should reduce repetition, not eliminate oversight.
- Test the exit path early: I would locate the settings for changing instructions, disconnecting an account, and ending use before I need them. Knowing where those controls are gives me confidence that convenience has not become dependence.
A fourth habit is to keep the app’s role narrow. I would not use a notification as a reason to change a long-term plan, and I would not judge performance from a single short period. Instead, I would decide in advance how often I will review the strategy and what kind of change would justify action. This protects the user from turning an investing tool into a source of constant market anxiety.
Who should try it, and who should wait
I think Autopilot is most suitable for a new or moderately experienced investor who wants a less intimidating path into investing, values a guided experience, and is willing to review the important choices personally. It may also suit someone who already has a plan and wants a more focused way to carry it out. The free price makes initial exploration easier, and the Everyone content rating keeps the product broadly approachable from an age-label perspective.
I would be more hesitant to recommend it to someone who needs money for a near-term purchase, has not built a basic emergency cushion, or expects an app to prevent losses. I would also point advanced users toward a fuller brokerage if they require detailed research, complex order management, or extensive customization. Someone with unusual tax, legal, or family circumstances should not mistake a streamlined investing workflow for individualized advice.
Privacy-conscious users should make their own permission and account-access decisions rather than accepting every prompt automatically. I appreciate the principle of visible user choice, but the responsible approach is to inspect each sensitive step on the device and within the account settings. That gives me a clearer understanding of what I am authorizing and keeps the relationship with the app intentional.
My cautious verdict after weighing convenience against control
Autopilot succeeds at making investing feel more approachable, and I can see why its audience has responded positively. Its 4.7 average and broad install base indicate strong reception, but I would treat those signals as a reason to investigate, not as a guarantee. The product’s real value depends on whether its guided experience matches the user’s need for control, explanation, and oversight.
My recommendation is cautious but positive: try it if you want a focused investing companion and are prepared to verify every important choice. Keep your own plan, review permissions, monitor account controls, and avoid using simplicity as a reason to skip research. If you want a complete brokerage toolkit or personal financial advice, choose an alternative that is built for those needs instead.
In short, I would use Autopilot as a deliberately supervised way to reduce investing friction, not as a hands-off substitute for judgment. That distinction is what makes the app useful for the right person and potentially unsuitable for the wrong one.
FAQ
What is Autopilot - Investment App and how does it work?
Autopilot - Investment App is designed to help users follow and manage investment strategies through a mobile interface. Depending on the available features and connected services, the app may track portfolios, display investment activity, and automate or mirror selected strategies. Before using it, review exactly how trades are executed, which accounts are supported, and whether the app acts as an advisory, brokerage, or portfolio-management tool.
Is Autopilot - Investment App safe to use with my financial accounts?
The app may require access to sensitive financial information or permission to connect with an investment account, so security should be a priority before downloading. Check whether it uses encryption, secure authentication, and reputable financial partners. You should also read its privacy policy carefully to understand what data is collected, how it is stored, and whether information is shared with third parties.
Can Autopilot automatically buy and sell investments for me?
Autopilot may offer automated investing or strategy-following features, but the exact level of automation can vary by account type, plan, and region. Some functions might only provide alerts or recommendations, while others could place trades after authorization. Always confirm whether transactions require your approval, how positions are selected, and whether you can pause or disable automation at any time.
Are there fees, subscription costs, or additional trading charges?
Before creating an account, carefully review all potential costs associated with Autopilot - Investment App. Expenses may include a subscription, management fee, brokerage commissions, fund expenses, foreign exchange charges, or fees from a connected financial provider. A free download does not necessarily mean the service is free, so check the current pricing page and understand when charges begin and how cancellation works.
Is Autopilot - Investment App suitable for beginner investors?
The app may be useful for beginners because it can simplify portfolio monitoring and make investment strategies easier to follow. However, convenience does not remove investment risk. New investors should understand that market values can fall, automated strategies can produce losses, and past performance is not a guarantee of future results. Start cautiously, learn the app’s controls, and never invest money you cannot afford to lose.


